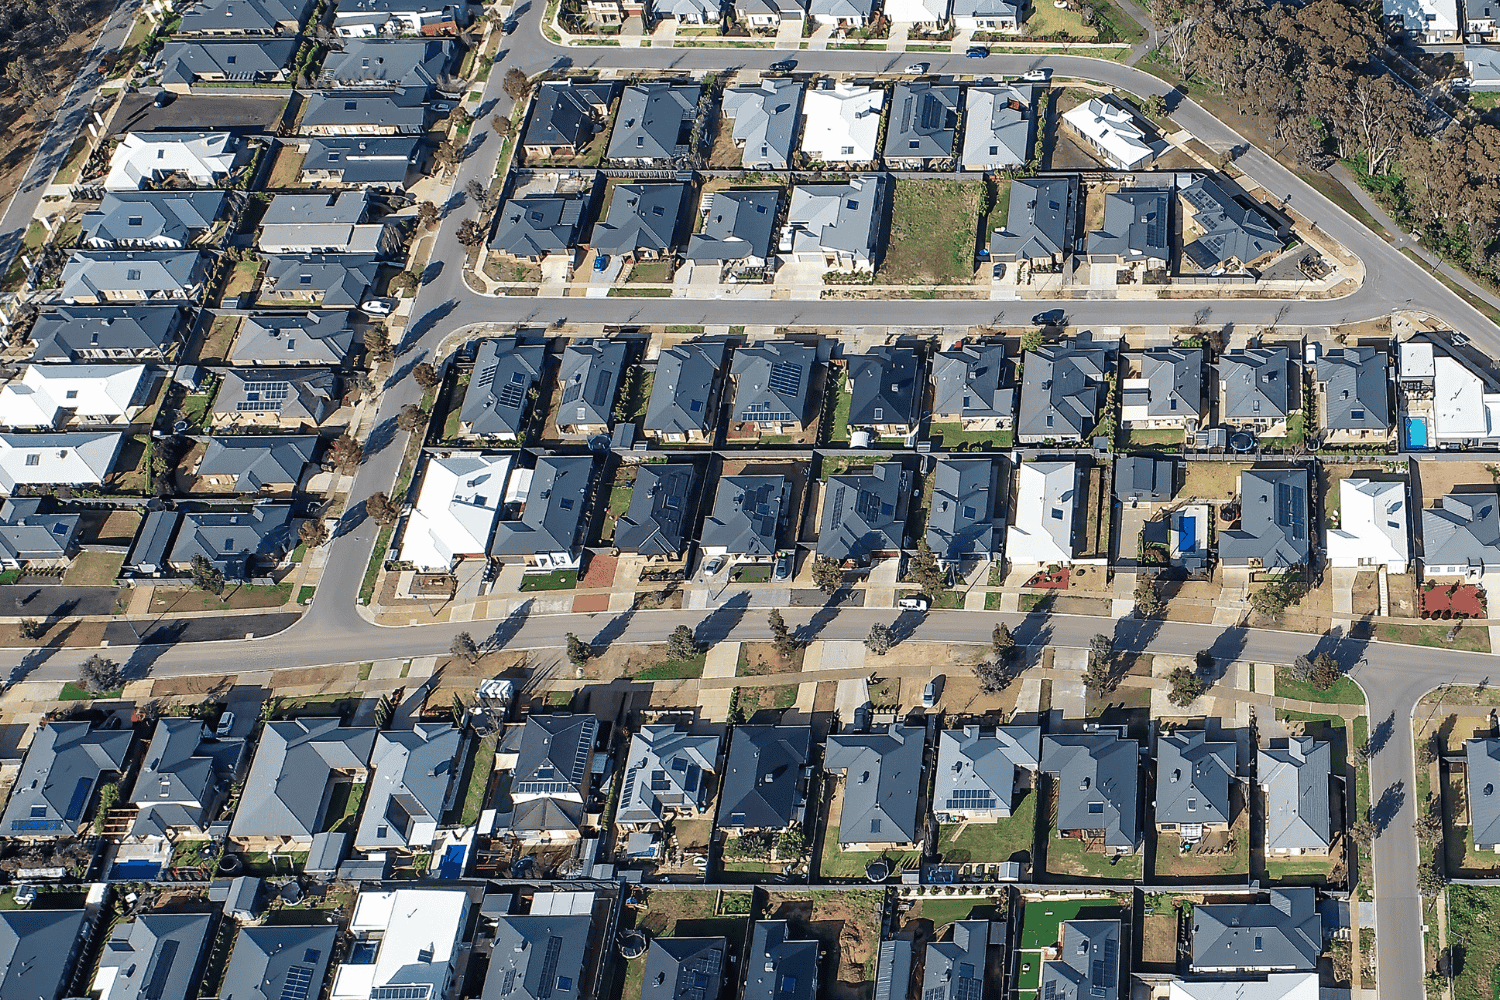
Australia’s housing market has reached an extraordinary point: house prices are falling in parts of the country, yet housing affordability is getting worse.
A median-income Australian household earning around $125,000 a year can just afford 12 per cent of homes sold nationally - with most of those being apartments. Mortgage repayments are consuming 35.5 percent of household income, higher than during the Global Financial Crisis.
If falling house prices aren't making housing more affordable, perhaps we have been asking the wrong question.
Australia doesn’t simply have a house price problem. We have a housing-system problem.
For years, governments have focused heavily on measures designed to manage demand or assist particular groups of buyers.
But you cannot sustainably make housing more affordable while making it harder and more expensive to produce.
Construction costs remain around 51 per cent above pre-COVID levels. At the same time, the National Housing Supply and Affordability Council estimates Australia’s target of 1.2 million new homes will not be reached until the December quarter of 2030.
We know we have a housing shortage.
Yet the economics of producing new housing remain increasingly difficult.
I have previously argued that Australians buying a new home are increasingly purchasing what amounts to a “house and tax package”.
GST, stamp duty, infrastructure contributions, development charges, land tax, compliance requirements and other costs all form part of the economics of delivering a home.
Then add land, labour, materials, finance, planning delays and the cost of holding land through an increasingly lengthy approval process.
The contradiction becomes obvious.
We say we desperately need more homes while making those homes increasingly expensive and difficult to deliver.
This isn't an argument for removing every taxor regulation.
Good planning, appropriate regulation and sensible investment all have a role to play.
But we need to be honest about the cumulative impact of policy.
Every additional cost, delay or layer of complexity has to be absorbed somewhere in the housing equation.
Ultimately, it flows through to the price of the home.
NAB chief economist Sally Auld recently told a Senate inquiry that meaningful improvement in housing affordability could take “the better part of a generation” to resolve.
That should be a wake-up call.
We cannot tell today's 25 and 30-year-olds that home ownership is something we might eventually fix when they are approaching 50.
Even if we dramatically increase housing supply, we still have to address whether Australians can actually buy those homes.
Across our businesses at White Picket Fence, we see this from several sides of the housing system.
We see people with stable employment and sufficient income to service a mortgage who nevertheless struggle to enter the market because they cannot accumulate a traditional deposit while paying rent and meeting rising living costs.
For many, saving a deposit has become a treadmill: rent makes it harder to save, while house prices and construction costs continue to move the goalposts.
That doesn't mean everyone should be encouraged to borrow more.
It means we should be willing to explore responsible finance models for eligible Australians who can demonstrate genuine capacity to repay, but are being held back by the deposit hurdle.
The housing debate therefore cannot simply be about making property prices fall.
We need to tackle both sides of the equation: the supply of homes and the ability of Australians to responsibly access them.
Housing doesn't get built simply because governments announce targets.
Developers need confidence to commence projects. Builders need sufficient margins to take construction risk. Investors provide capital and demand that supports new supply. Lenders need confidence to fund projects and buyers. And buyers need confidence to purchase.
When one part of that chain retreats, the consequences flow through the entire system.
Housing is an ecosystem. Pull one lever and another moves.
This is particularly important as governments consider changes to housing and investment policy.
Whatever the policy objective, we need toconsider its cumulative impact on investor confidence and new housing supply.
Australia cannot deliver 1.2 million homes through government investment alone.
We need private capital, developers, builders, lenders, investors and buyers all willing to participate.
If investing in housing becomes less attractive at precisely the time we need more investment in housing, we should not be surprised when supply suffers.
A policy designed to improve affordability can ultimately make housing less affordable if its unintended consequence is fewer homes being built.
That is the danger of treating housing policies in isolation.
For too long, the housing debate has centred on one question:
“How do we make houses cheaper?”
It is the wrong question on its own.
The better question is: “How do we make significantly more homes commercially viable to build, while giving more Australians a responsible pathway to buy them?”
That requires action on three fronts.
First, we need to make it easier and more commercially viable to deliver new housing.
That means looking seriously at unnecessary taxes, charges, planning delays, regulatory complexity and construction costs that add to the price of every new home.
Second, we need to restore confidence across the housing ecosystem.
Developers, builders, investors and lenders need an environment in which projects can stack up commercially and capital can flow into new supply.
Third, we need responsible innovation in housing finance.
For eligible Australians who can genuinely afford the repayments, we should be open to new models that address barriers such as the deposit without compromising responsible lending.
There is no single policy that will solve Australia's housing crisis.
But there is one thing we should stop doing.
We should stop treating housing affordability, housing supply and access to finance as separate problems.
They are deeply connected.
We cannot tax, regulate and delay our way to affordable housing.
Nor can we simply wait for prices to fall and hope affordability takes care of itself.
Australia needs more homes.
Builders and developers need the confidence and commercial conditions to deliver them.
And Australians need realistic, responsible pathways to buy them.
Get those three things working together, and we might finally start solving Australia’s housing crisis rather than simply trying to manage it.
Expert insights, market analysis, and practical guidance to support confident homeownership outcomes.